Publié le 28 septembre 2026 · 5 min read
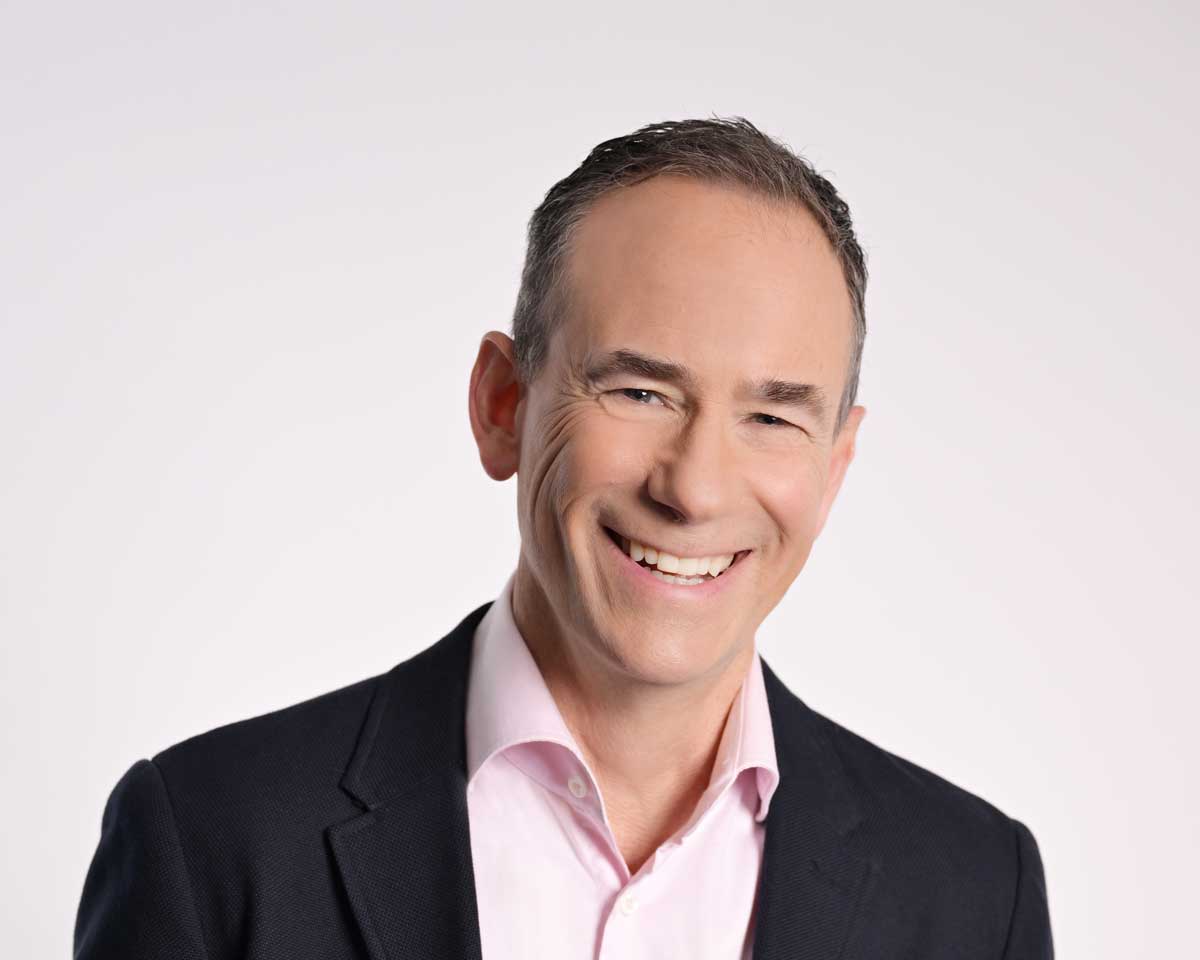
For this week’s MVP, we’re chatting with Bruce Sellery.
Quick and fast finance rules are catchy and convenient, none more so perhaps than the 30% rule—the long-standing guideline that says one shouldn’t spend more than 30% of one’s overall income on housing costs. The Canada Mortgage and Housing Corporation’s been touting the rule since officially adopting it in the ‘80s, but a generation before that, the accepted norm said 25% was too much. And finance experts still debate whether or not the old 30% chestnut still deserves its spot in the financial playbook.
De notre commanditaire
But does any of this matter since most of us don’t know our percentage anyway? The majority of people–68%, according to a new survey of more than 1,500 Canadians by Credit Canada—can’t say with confidence how much of their household income goes towards their housing, even as housing prices continue to climb. Of those who can, meanwhile, almost three-quarters were above the 30% threshold anyhow.
Credit Canada recently launched their “Keys to Home Confidence” educational program, a good fit for the 68% of us who aren’t sure of our spending percentage. We asked Bruce Sellery, Credit Canada’s CEO, if and how the 30% rule holds up and how to know if you’re among the “house poor.”
What does being “house poor” mean to you?
“House poor” is when you buy a home but when you’re living in it, you have no money for anything else important, and your experience and your life is affected. I remember hearing the term for the first time in the mid-‘90s.
A colleague told me she’d bought a house. Although it was a great house, she could afford nothing else. I don’t think she planned that. People don’t ever plan to be house poor; it’s more that they don’t plan for unforeseen expenses. They’re not prepared for a broken furnace or leaky roof, but they’ve got Corian countertops and wall-to-wall hardwood. Houses are bigger and bougier than before.
You’re making having any sympathy for house-poor people difficult.
It’s definitely something you do to yourself. There’s context though and a number of reasons why this happens: The reality is that house prices have been ridiculous for the last 20 years, and incomes haven’t risen alongside that.
We have a false sense of what we should expect in terms of interest rates. Historically, they’ve been more like 7% but as high as 18% in the ‘80s. We now have a sense of entitlement that we deserve interest rates that are virtually zero. That’d be great, but it’s not the case.
We also want more out of our houses than a generation ago. In an era of HGTV and Instagram influencers and house staging, there’s a lot of pressure. If you buy a house that was staged to look like it’s in a magazine, then you show up with all your IKEA furniture, you may think it’s not good enough. Maybe you renovate your kitchen, but now your old table looks thrifted. It never ends.
Should the 30% rule also apply to my new table?
Technically, yes. The rule covers the mortgage, essential bills, plus HOA (homeowners’ association) fees if you’re in a condo. Also maintenance, home repairs and furniture, everything having to do with your house. Add all those up and you’ll soon realize how far away from 30% you are.
I believe there’s a role for “rules of thumb,” and they’re a starting point for people. But this one is just completely inaccurate. Most people look at that and feel immediately disempowered. So it’s not helpful. And it’s problematic too, because it doesn’t account for the region. Living in a big city is very different from living in a rural area.
The price of real estate is more expensive. And even though incomes might be higher, there are households in some places where a 30% housing budget will never happen. There’s just no way.
On the other hand, if I made a million bucks a year, would it still be bad to spend more than 30% on my house?
You can do whatever you want, first of all. If you make $1 million a year and you choose to go to Vegas and gamble it all away, it’s your money.
I don’t love rules and I don’t think it’s about percentages. It’s about budgeting and whether or not you’re in a deficit, just to live the life you want to live.
I want people to think holistically about what they want for their life today and what they want for their life at age 90. Toggling between “present you” and “future you” is an exceedingly difficult thing for a human being to do. It’s really hard, but critical.
Maybe it’s worth it to you to live like a monk in your new big house. But if you’re spending that much on your house, where are your retirement savings? How much have you saved for the kids’ education? Are you taking any vacations?
These things are all important, too, and you’ll be making some big trade-offs.
What would you say to someone who’s about to close on a big house they might not be able to afford?
Before someone goes on a house hunt, they should analyze, brainstorm and imagine a change of sustainable spending. It’s easy to plug some figures in to get the mortgage payment, then add 1% to 2% on house maintenance, of course.
Then there’s retirement and the kids’ education and activities. Recreational hockey is like $4,000 a year, but if it’s really important to your kid, you’ll probably make some trade-offs to make it happen.
Your interests are important, too, so make a list of those and include them in your budget.
If you’re in a deficit, then you need to brainstorm ways to increase income or cut spending, which could mean a smaller house. Maybe you need to call it and say “It doesn’t work and we can’t afford this house.” Make the choice—but make sure you’re making it with eyes wide open.
Read more from this issue of The Get:
Rosemary Counter
Rosemary Counter is a Toronto-based writer and journalist whose reporting and essays have appeared in The New York Times, Vanity Fair, The Guardian and others.
The Get is owned by Neo Financial Technologies Inc. and the content it produces is for informational purposes only. Any views and opinions expressed are those of the individual authors or The Get editorial team and do not necessarily reflect the official policy or position of Neo Financial Technologies Inc. or any of its partners or affiliates.
Nothing in this newsletter is intended to constitute professional financial, legal, or tax advice, and should not be the sole source for making any financial decisions. Past performance is not a guarantee of future results. Neo Financial Technologies Inc. does not endorse any third-party views referenced in this content. Always do your due diligence before deciding what to do with your money.
© 2026 Neo Financial Technologies Inc. All rights reserved.