Neo Advance vs. Money Mart review: Why a payday loan isn’t worth it
Published on October 23, 2026 · 5 min read
For decades, Money Mart has been lending to Canadians with the promise of accessible, short-term cash. Access to funds may be the pitch, but what that access costs is just as important. And when you look at what a Money Mart payday loan can actually cost you, the picture changes fast.
Neo Advance is a new cash advance that covers the same cash gap at 0% interest. It also does something Money Mart doesn’t: Neo Advance reports every repayment to both major credit bureaus, so more lenders can see that you have a history of repaying what you borrow. Having that track record on your credit file can help when you eventually apply for credit cards, loans and even a mortgage.
Here’s a closer look at how Money Mart and Neo compare, and how much each actually costs you.
Neo Advance vs. Money Mart Payday Boost: At a glance
Reading this article on mobile? Scroll to the right to see the full table.
| Feature | Neo Advance | Money Mart Payday Boost |
|---|---|---|
Cash advance limit | Up to $500 | $100 to $1,500 |
Hard credit check | No | No |
Availability | Canada-wide | Available in Alberta, B.C., Ontario, Saskatchewan, Nova Scotia, and Manitoba |
Cost | Included with Neo Start (coming soon), Build, and Grow memberships: • Start: $0 when you deposit your payroll or $1,000 monthly into your Chequing account, or $4.99 a month¹ • Build: $0 with a Neo World Elite® Mastercard², or $9.99 a month • Grow: $14.99 a month | Charges a $14 fee for every $100 borrowed. This is charged every time you borrow, plus penalties for missed or late payments. |
Interest | 0% interest | Fee of $14 per $100 borrowed translates to 365% APR |
Repayment period | 34 days | As little as 1 week |
Funding speed | Instantly via the Neo Chequing account | Up to one business day |
Credit bureau reporting | Equifax and TransUnion®, so more lenders can see your on-time repayments | No, only negative behaviour like missed payments are reported |
Credit progression | Yes, on-time repayments can build credit history and unlock the path to secured cards, unsecured credit cards, and more | No |
What is the Money Mart Payday Boost?
Money Mart's Payday Boost is a short-term payday loan available in Alberta, B.C., Ontario, Saskatchewan, Nova Scotia, and Manitoba. Depending on the province you reside and your income, you can borrow between $100 and $1,500 and repay it in a lump sum on your next payday.
The fee is $14 for every $100 you borrow, which is the legal maximum in provinces like Ontario. Funds arrive within the same day when you transact at a physical branch, while online funding can take up to one business day.
On the surface, $14 doesn't sound like much, but this is where three very important letters come in: APR.
Wait, what is APR anyway?
APR, or annual percentage rate, is the rate at which a loan costs over a year. Think of it as the price tag on a loan.
Because payday loans are typically repaid in about two weeks, a $14 fee to borrow $100 comes out to be surprisingly expensive when you look at it annually. On a two-week payday loan, that works out to around 365% APR. Borrow $300 and roll that pattern forward for a year? That’s $1,095 in fees to borrow $300 once.
Sure, most people don't roll over a payday loan for a year. But it’s important to understand what short-term fees can actually amount to in the long-term.
What if I miss a payment?
Missed payments can lead to big penalties. If you miss repaying a Money Mart payday loan, you may be subjected to late fees and non-sufficient funds (NSF) charges from your financial institution, plus additional interest.
What is Neo Advance?
Neo Advance is a cash advance that works with the Neo Chequing account. It has 0% interest, and no credit score is required. When a sudden expense comes up before payday, Neo Advance can help cover the gap. Funds instantly land in your account, and you can spend it via the Neo Money™ card, pay a bill in-app, or withdraw the cash from an ATM.
Access comes with Neo memberships like Start (coming soon), Build, or Grow. Here’s what memberships cost, and the maximum Advance each unlocks.
Reading this article on mobile? Scroll to the right to see the full table.
| Neo membership | Neo Advance limit | Monthly fee |
|---|---|---|
Start (coming soon) | Up to $100 | $0 when you deposit your payroll or $1,000 monthly into your Chequing account, or $4.99 a month¹ |
Build | Up to $300 | $0 with a Neo World Elite® Mastercard², or $9.99 a month |
Grow | Up to $500 | $14.99 per month |
You might get the full Advance limit on day one. The amount you can borrow is based on your cashflow and your repayment track record. That amount can climb within your membership maximum as you use Neo Advance responsibly.
Here’s how it works:
- Open a Neo account and choose a membership that includes Neo Advance (Start, Build or Grow).
- Instantly access an amount up to your eligible limit.
- Repay as deposits come in. Payments are reported to both TransUnion® and Equifax to help build your credit history.
From our sponsor
Neo Advance vs. Money Mart: Features compared
Credit building
Every time you use and repay Neo Advance, that activity is reported to both TransUnion® and Equifax. That’s the same kind of activity lenders look for when you apply for credit cards or loans.
Paying off a Money Mart payday loan does not build that kind of history. A year of on-time payday repayments can still leave you in the same spot next year, still needing a short-term advance to cover a gap. You’re paying to borrow, and getting nothing back on your credit file for it.
Repayment flexibility
With Money Mart, your full loan amount plus fees is due in one lump sum on your next payday. If you’re already stretched thin, coming up with the full repayment can push you into re-borrowing. That’s how a single advance turns into a cycle of fees.
Neo Advance works differently. There's no lump sum deadline to scramble for. Your advance repays automatically when your next deposit arrives, meaning you have no lump sum deadline to worry about. The money comes in, the advance clears, and your limit resets, ready to use again if you need it.
Funding speed
With Neo, your advance hits your Neo Chequing account instantly. With Money Mart, in-person funding can land the same day, but online can take up to one business day. If you’re in a pinch, that wait matters: a bill due today, a declined transaction, or a gap that won’t hold until tomorrow.
Availability
Neo Advance is available Canada-wide. Money Mart’s online payday loans are only available in Alberta, B.C., Ontario, Saskatchewan, Nova Scotia, and Manitoba. If you're outside those provinces, getting a Money Mart payday loan online may not be an option.
Neo Advance vs. Money Mart: Which works for you?
Money Mart gives Canadians access to fast cash at a high cost, but at 365% APR, it’s one of the most expensive ways to borrow money in Canada. And because Money Mart does not report to credit bureaus, your payments do not contribute to building your credit history.
Neo Advance covers the same gap with a predictable monthly membership fee (that gives you access to credit monitoring and other tools). It helps you cover a cash gap while laying the groundwork for you to progress beyond short-term borrowing.
Read more about cash advances:
The Neo Editors
Neo’s editorial team does the heavy lifting—vetting the facts, stripping away the jargon, and breaking down complex mechanics—to bring you straightforward guides you can use to build credit and chart your financial journey.
Related Posts
View All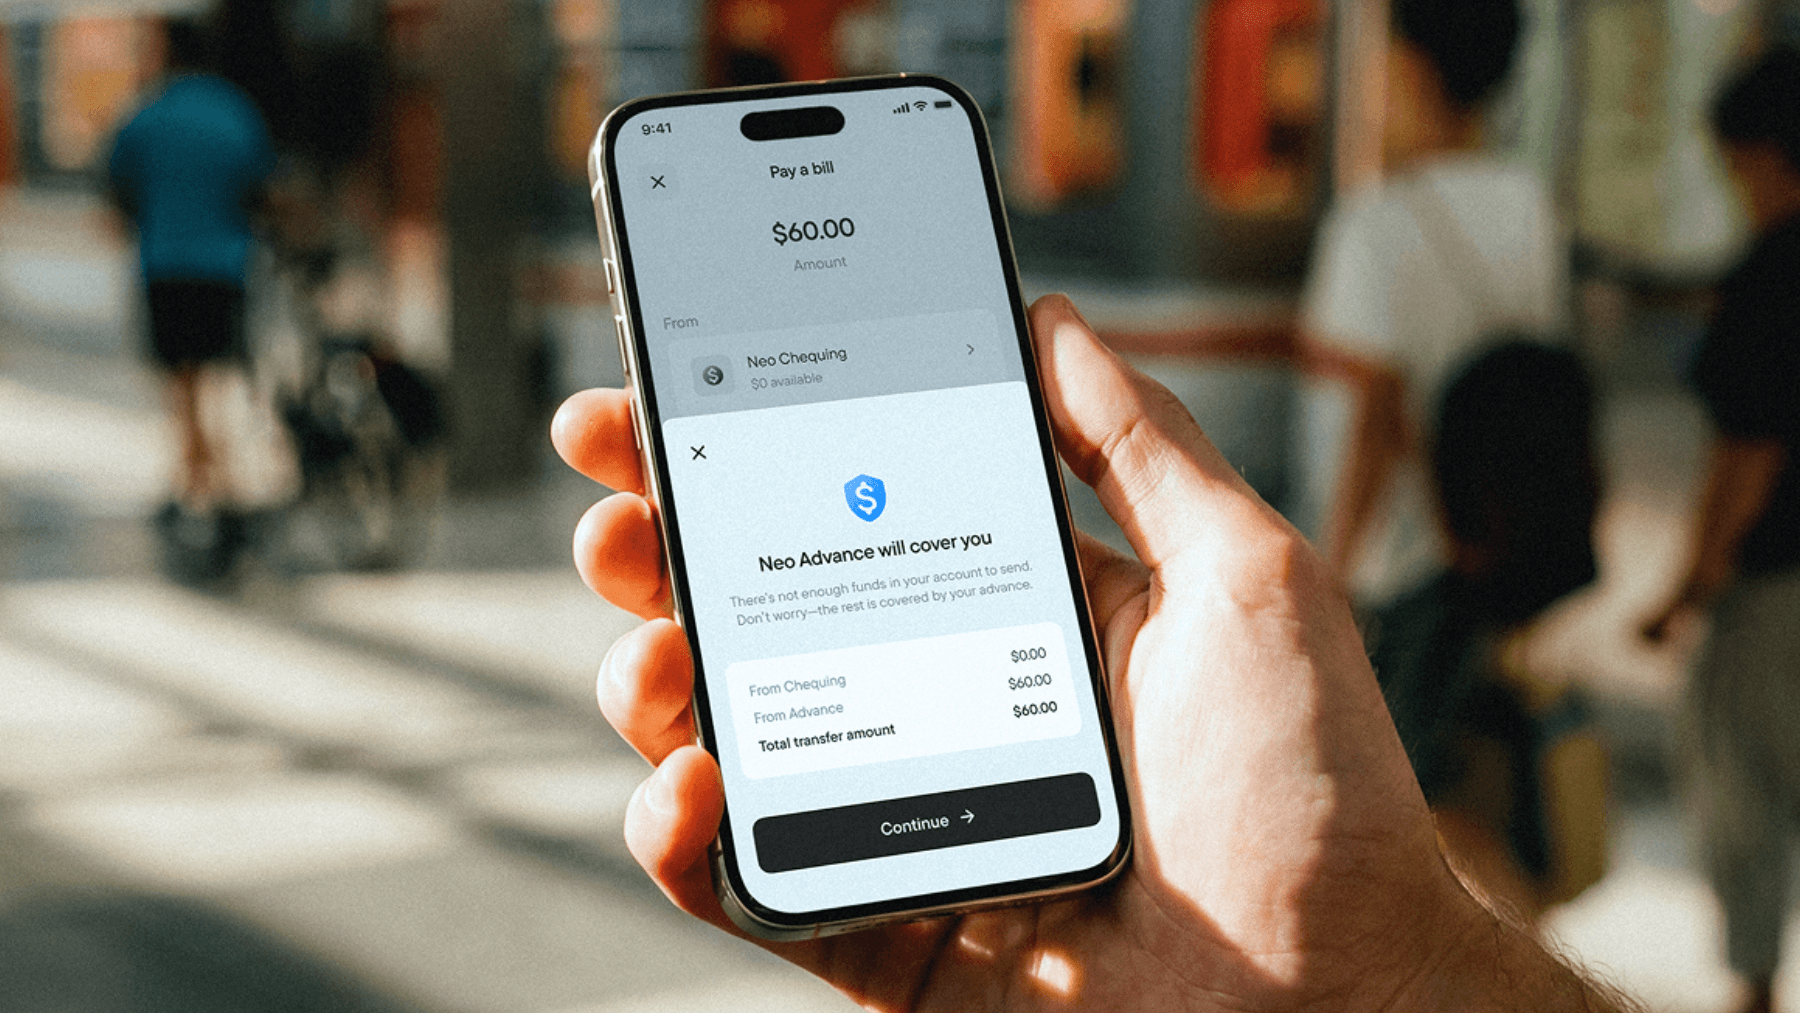
Neo Advance vs. Nyble: Which cash advance is right for you?
Both skip interest and a hard credit check, but only one gets you cash instantly, reports to both bureaus, and moves you forward after payday.
Neo Advance vs. KOHO Cover: Which cash advance builds credit?
A cash advance can get you through the week. But only one of these actually moves your financial life forward.
Budgeting tips for students in Canada (and how to actually stick to one)
When you’re a student, money rarely shows up in tidy paycheques, and classic budgeting rules don’t always fit. Here’s how to build a plan when you’re at school.