Published on November 2, 2026 · 4 min read
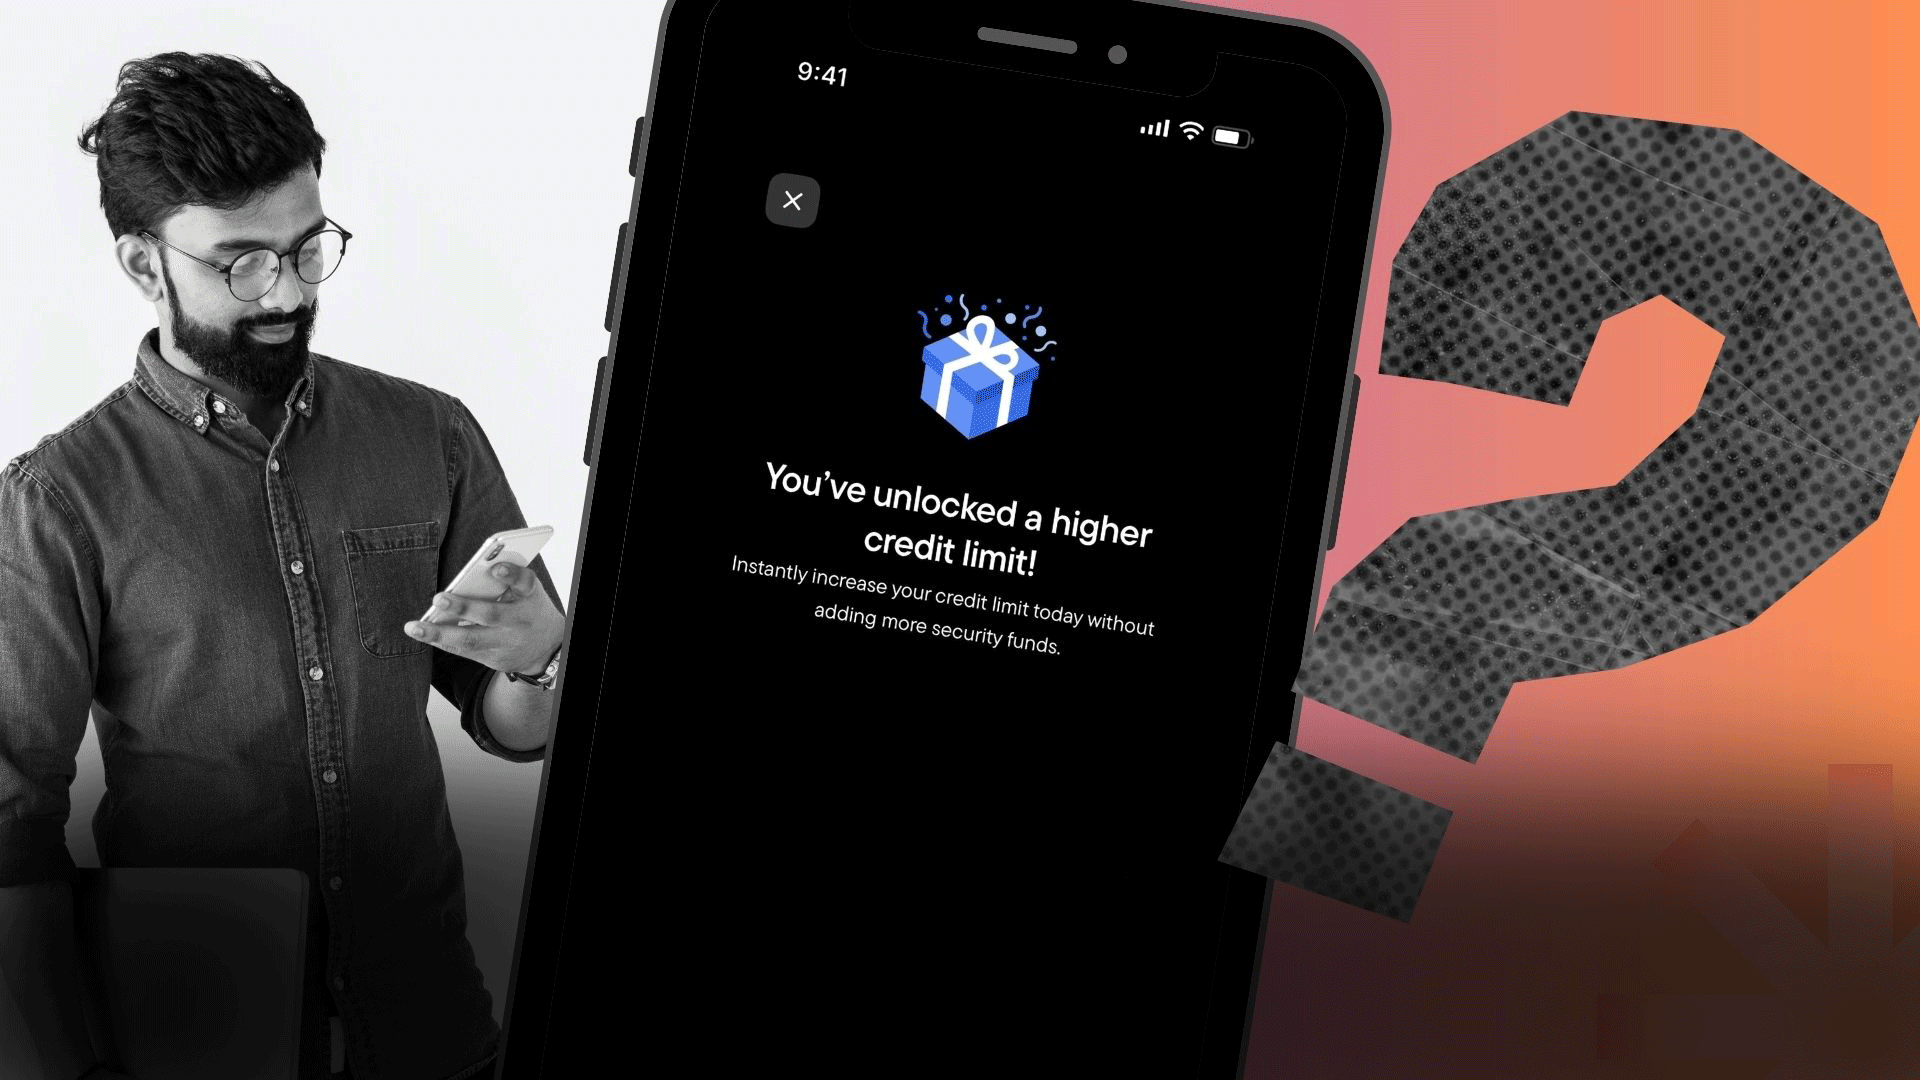
Here is the answer to this week’s reader question about credit limit increases.
How do I get my credit limit increased?
–Bahogana
How to increase your credit card’s credit limit
The simplest way to increase your credit limit is to simply ask. How you do it depends on your credit provider, and whether you typically connect online, on the phone, in person or even through an app.
The request doesn’t mean the approval is automatic, though. Lenders typically consider a few different factors: your payment history, how long you’ve had the account, your current income, your existing debt levels—that’s a pretty important one—and your credit score and overall credit profile.
If you’ve been making your payments on time, keeping the balances manageable, and your income has increased since you opened the account, you would have a pretty strong case.
Should you accept a credit limit increase offer?
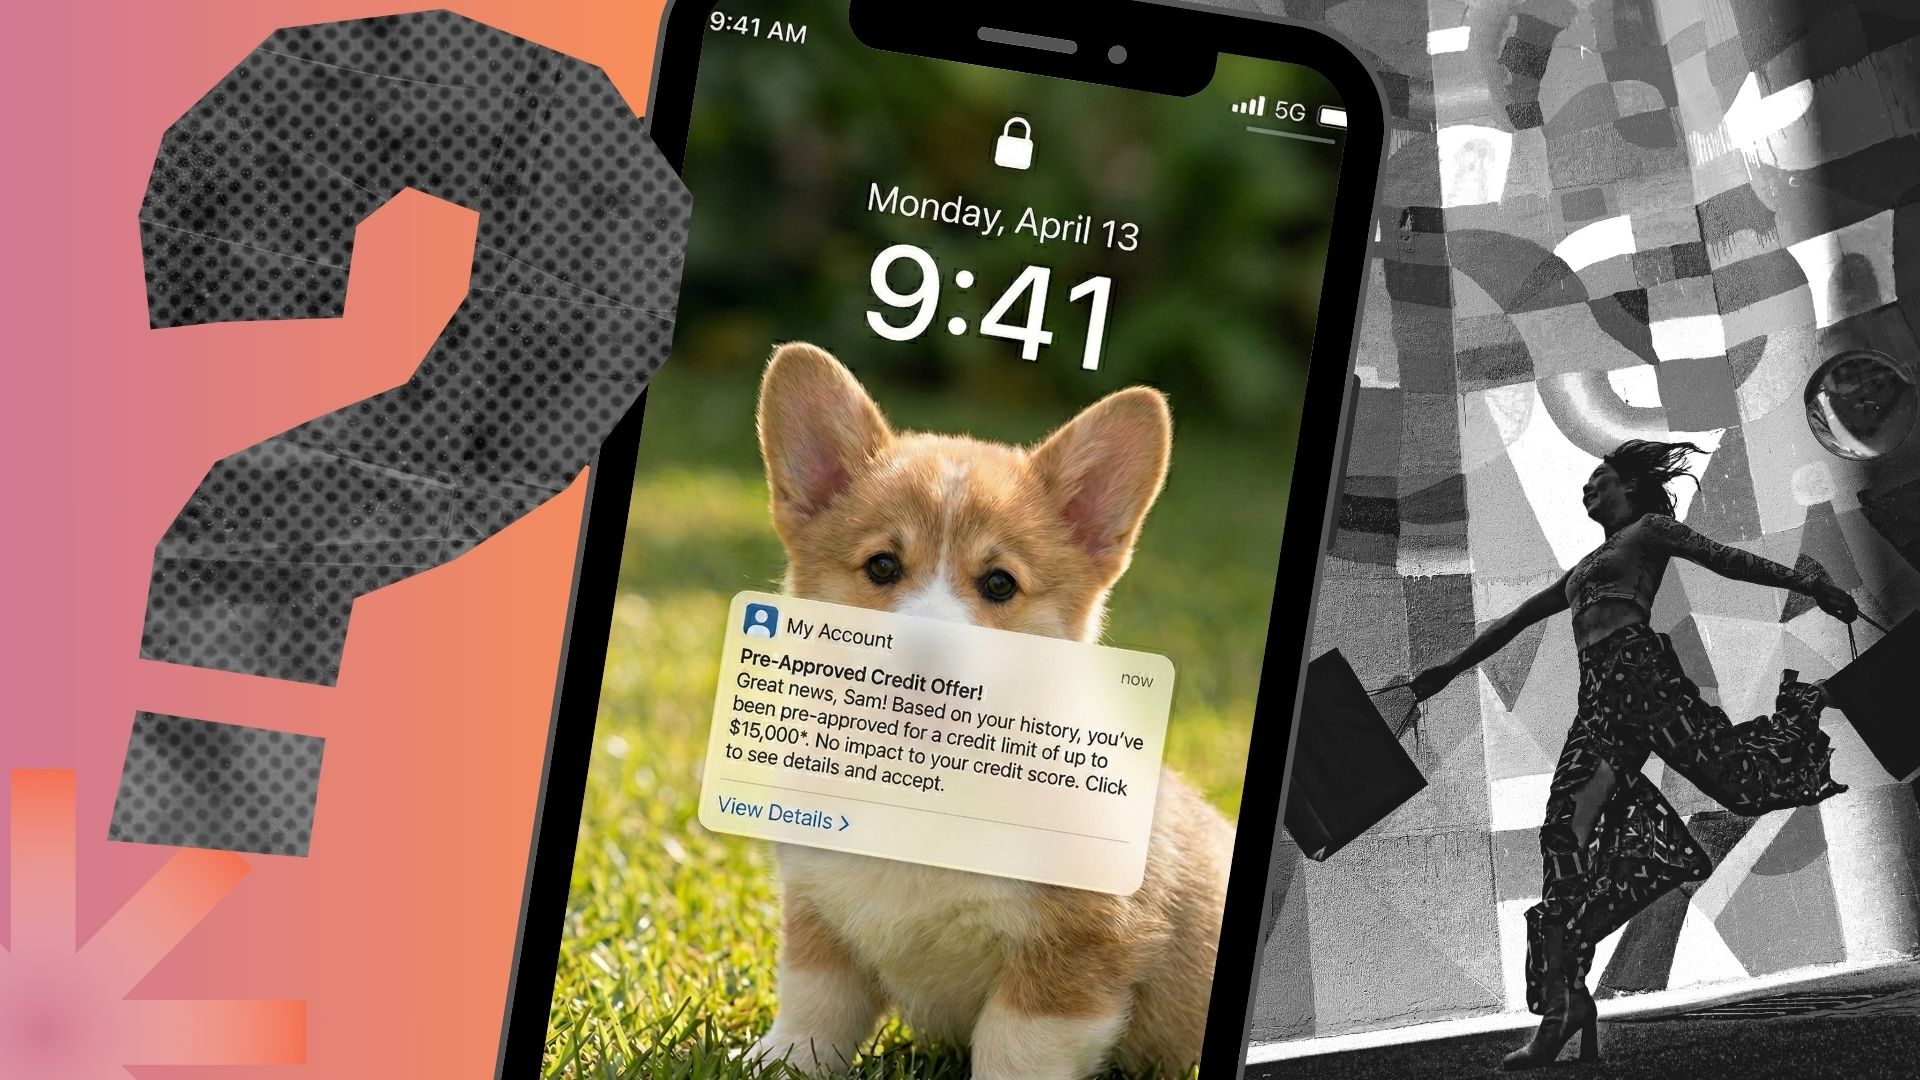
Lenders often proactively offer credit limit increases to Canadians who have demonstrated responsible credit use over time by, for example, making regular payments and never missing one.
So, even if you don’t ask, a credit increase will eventually come to you more often than not, and then you can either accept or reject it.
If you genuinely feel that “If I increase this limit, it might put me in a tricky situation because I know myself and my spending,” then it’s OK to say no.
It will eventually be offered again. But if you are pretty on top of your finances, then it doesn’t hurt to accept that credit limit increase, even if you don’t need it, because it can positively affect your credit report—as long as you use credit responsibly.
The pros of raising your credit limit
Number one benefit: It lowers your credit utilization ratio, the percentage of available credit that you’re using. The rule of thumb is to keep it at 30% or less. Increasing that limit mathematically decreases your utilization, and generally that’s viewed a lot more favourably by lenders.
Another pro would be having more financial flexibility. Having that higher limit can provide some breathing room for unexpected expenses and larger planned purchases.
It also reduces the risk of maxing out your card. Being close to your credit limit can negatively affect your credit profile, so having that increase does give you a bit of wiggle room.
The cons of raising your credit limit
Having a higher credit limit can uncover underlying financial challenges, such as when someone is constantly increasing their limit because they’re using credit to pay for living expenses like housing or utilities.
Increasing the limit might cover you that one time, but it just delays the need to deal with the root issue that’s causing that financial hardship.
A higher limit also means more of an opportunity to spend. It’s not free money—you do have to pay it back. And if it takes a while to pay back, you have to consider the interest that gets tacked on. So you want to be a bit more conscientious about your spending when that limit increases.
The higher the limit, the bigger the potential for debt. If additional credit encourages larger balances, then that can lead again to more interest charges, a longer time to repay and greater financial stress when money now has to be used toward debt repayment rather than your usual expenses.
From our sponsor
How to manage debt
If needing more credit is a way to deal with hardship or keeping up with debt payments, or you increased that credit limit and now you’re having difficulty repaying that debt, get in touch with a non-profit credit counselling organization, whether it is the Credit Counselling Society or another organization. They can help you explore options when it comes to paying down debt in a way that’s manageable for you.
And if it’s a matter of, “Hey, I’m thinking about getting that credit limit increase, but I’m not really sure if it’s good for me,” you can still call us and talk with a counsellor. It’s free, it’s confidential and it will give you the opportunity to make an informed decision.
Read more from this issue of The Get:
Ali Harris-Saunders
As a certified financial counsellor and wellness coach, Ali Harris-Saunders blends all aspects of wellness together through her work as corporate and community relations manager with the Credit Counselling Society, and the founder of Wood & Water Holistic Fitness.
Kat Tancock
Kat Tancock is a writer, editor and translator based in British Columbia. Her writing on personal finance has appeared in the Globe and Mail, MoneySense, Asparagus and Chatelaine.
The Get is owned by Neo Financial Technologies Inc. and the content it produces is for informational purposes only. Any views and opinions expressed are those of the individual authors or The Get editorial team and do not necessarily reflect the official policy or position of Neo Financial Technologies Inc. or any of its partners or affiliates.
Nothing in this newsletter is intended to constitute professional financial, legal, or tax advice, and should not be the sole source for making any financial decisions. Past performance is not a guarantee of future results. Neo Financial Technologies Inc. does not endorse any third-party views referenced in this content. Always do your due diligence before deciding what to do with your money.
© 2026 Neo Financial Technologies Inc. All rights reserved.